Investors in the semiconductor space have enjoyed a wild ride since early 2023, watching giants like Nvidia and Micron post staggering gains. However, despite these historic climbs, several key players are currently trading well below their peak values. While some might see this dip as a sign of cooling interest, evidence suggests that Wall Street has simply been playing catch up with reality. Analysts have consistently underestimated the sheer scale of investment going into artificial intelligence infrastructure, creating a gap between market expectations and actual corporate spending.
The numbers tell a compelling story of missed projections. Initial estimates for capital expenditures among the biggest tech hyperscalers were quickly eclipsed by surging demand. What was once projected to be roughly 546 billion dollars in spending this year is now trending toward 800 billion by 2026. Looking further ahead to 2027, forecasts have leaped from 630 billion to an estimated 1.1 trillion dollars, with some optimistic projections suggesting figures as high as 1.6 trillion if emerging specialized firms are included in the tally. This pattern of underestimation indicates that the appetite for AI hardware remains far more aggressive than many analysts originally presumed.
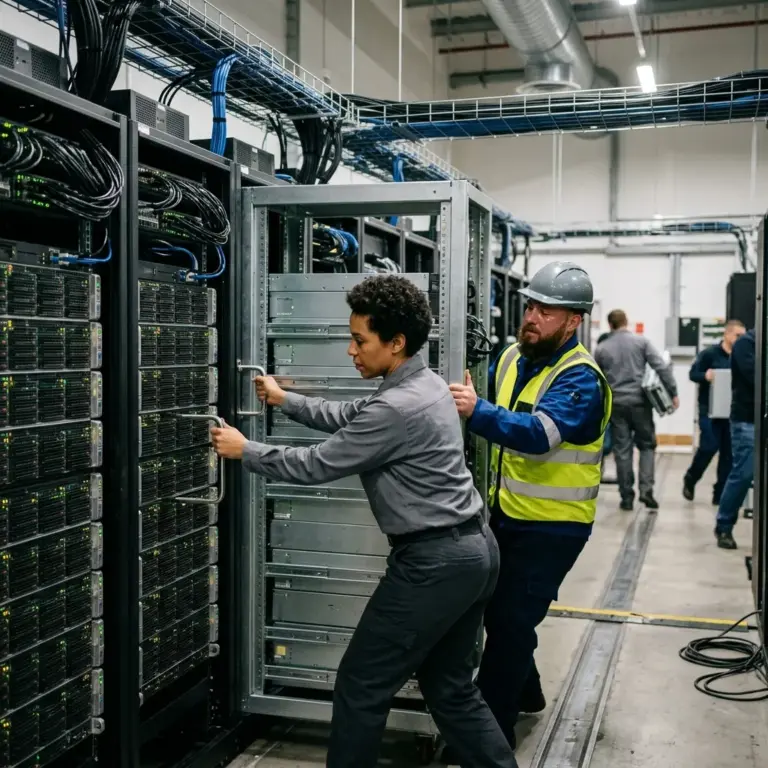
This massive wave of spending directly benefits a core group of chipmakers who provide the essential building blocks of the AI era. Nvidia continues to dominate the GPU landscape, while Broadcom secures its place through custom accelerators and critical data center networking tools. Meanwhile, AMD provides vital competition in both CPUs and GPUs, and Micron supplies the high bandwidth memory necessary to keep these powerful processors running efficiently. Each company brings a different strength to the table, ensuring that regardless of which specific architecture wins out, the underlying need for silicon persists.
From a valuation perspective, these stocks offer varying levels of entry appeal based on their growth potential relative to price. Micron currently appears as one of the most attractive options given its low price to earnings to growth ratio and significant implied upside according to analyst targets. While individual winners are always hard to predict in such a volatile sector, the overarching trend suggests that diversification across these four leaders is a prudent strategy. As long as big tech continues to pour trillions into AI infrastructure, these semiconductor firms remain the primary beneficiaries of a mistake made by cautious forecasters on Wall Street.