Washington’s tariff pressure is giving Alaska LNG something its economics have struggled to secure: a potential investor. Discussed for decades, the costly and technically complex project has regained momentum under President Donald Trump, who is using tariff threats to press foreign partners into backing it. South Korea is now at the centre of that effort, as Seoul’s bid to protect access to the US market becomes a negotiation over financing one of America’s most expensive energy developments.
The question is whether that pressure can produce a commercially viable investment. Washington’s threat of 25% tariffs on Korean exports led to an arrangement, lowering the rate to 15% in exchange for $350 billion in investments and $100 billion in US energy purchases. South Korea’s parliament passed corresponding legislation in March 2026, with negotiations moving toward specific energy projects in September.
On October 1, Seoul outlined potential investments including a 6.47 GW gas-fired power project in Texas serving AI data centres from 2029, and eight US nuclear reactors costing a combined $120 billion, including two using Korea’s APR-1400 design. Alaska LNG was also under review, conditional on commercial and legal requirements being met and that condition is what matters. In September, President Trump had already announced that South Korea was to pay more than $50 billion toward Alaska LNG at an event attended by Alaska officials and Glenfarne Chief Executive Brendan Duval. Seoul’s conditional review falls well short of that commitment.
Owned 75% by Glenfarne and 25% by the state of Alaska, the proposed $45 billion–$54 billion development would transport North Slope gas to domestic consumers and ultimately an export terminal at Nikiski in south-central Alaska. However, the project has a fundamental disadvantage which is in its immense cost of connecting remote reserves to customers: treatment facilities and a roughly 1,300-kilometre (807-mile), pipeline must precede export revenues.
Geography of the project is the main issue. Much of the pipeline would be buried across difficult terrain, including shifting permafrost and mountain crossings reaching 1.5 km (5,000 feet). About 54% can be constructed only during summer, making missed construction windows a significant delay risk. Unresolved state-tax arrangements and domestic cost allocations add uncertainty over who absorbs possible overruns, including whether Alaskan households could face higher gas and electricity bills. Alaska must build exceptionally expensive infrastructure simply to reach the starting point of competing exporters.
Capital intensity approaches $2.7 billion per million tonnes of annual LNG capacity (in comparison to an $898 million/tonne for Qatar’s North Field East and $762 million/tonne for Cheniere’s Corpus Christi Stage 3). Development would proceed in phases, beginning with the pipeline that would feed the local market before the larger export component (first exports are targeted for 2031). This means that financing and cost recovery during the domestic-supply phase is yet another complication for the matter.
Asian commitments have so far been considerably narrower than Trump’s announcements. In July 2025, he said Japan would form an Alaska LNG joint venture under its $550 billion US investment vehicle. Alaska LNG subsequently disappeared from Japan’s list of potential investments. Japanese participation instead centred on an autumn 2025 letter of intent involving Jera and Tokyo Gas to purchase 1 million tonnes of LNG annually for 20 years.
Korea’s Posco International has similarly signed a non-binding agreement to buy 1 million tonnes annually for 20 years and supply a significant share of pipeline steel. Taiwan, Thailand and TotalEnergies have also expressed potential buying interest. Such arrangements indicate demand, but do not settle construction financing or risk allocation.
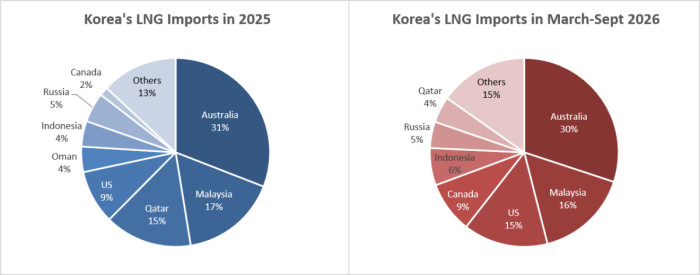
South Korea nevertheless still has substantial reasons to maintain access to American LNG. Its annual demand of 47.8 million tonnes dwarfs Posco’s proposed Alaska purchases. In 2025, the US supplied 4.4 million tonnes, behind Australia’s 14.7 million, Malaysia’s 7.9 million and Qatar’s 7.2 million. That balance shifted after the US-Iran conflict began in late February and Qatar effectively stopped exporting LNG. Korean imports from the US rose from 200,000 tonnes in March (out of total 3.1 million tonnes), to 1 million tonnes in July (out of 3.7 million tonnes). America became a leading supplier alongside Australia.
Yet greater reliance on US supply coincides with weakening Korean LNG demand. Net-zero policies are gradually reducing consumption, while wartime price increases prompted temporarily higher coal-fired generation and subsequent lower gas burning. Over the summer months, South Korea’s gas-fired power generation fell 9% year-over-year to an average 13 GWh. For reference, Korean coal usage is so far up 18% in 2026 to date, averaging almost 15 GWh throughout January-July. Milder summer temperatures also softened electricity demand during the usual summer and early-autumn peak.
When it comes to competing with European buyers of US LNG, Alaska offers a tangible advantage. US Gulf Coast shipments to South Korea around the Cape of Good Hope take approximately 40–45 days, with current freight estimated at around $42,000/day. Panama offers a shorter route, but transit restrictions, queues and canal charges make it less attractive even in comparison to the Cape of Good Hope route. In contrast, possible Nikiski-to-Korea voyages would take roughly 10–12 days, avoiding canals and major chokepoints.
However, South Korea can already access Pacific LNG without financing Alaska’s pipeline. LNG Canada, the venture backed by Shell, Petronas, PetroChina, Mitsubishi and Korea’s own KOGAS, began exports in July 2025 and already shipped 1 million tonnes to Asian markets this September. Its upcoming expansion to 28 million tonnes annually (approved late last month) would increase competition for the buyers Alaska needs. Shorter voyages are valuable, but Alaska has no monopoly on them.
Seoul’s caution therefore predates the current negotiations. Last year, South Korea’s trade and industry minister described Alaska LNG as high risk and an unviable investment option. However, tariff pressure has made repeating that judgment diplomatically harder, without resolving the underlying economics.
For now, Seoul will most likely try to gain time before making a diplomatically risky announcement of not participating in the project. Trump’s signalling of Korean investment into an unspecified $8.4 billion enhanced oil recovery project could offer this alternative. Such projects use injections of steam, gases or chemicals to extract additional crude. Too few details are available to assess this proposal, but it could give Seoul another way to demonstrate investment cooperation while limiting exposure to the commercially questionable Alaska LNG project.
This post appeared first on https://oilprice.com